Dollar eases as traders brace for U.S. CPI after jobs jolt
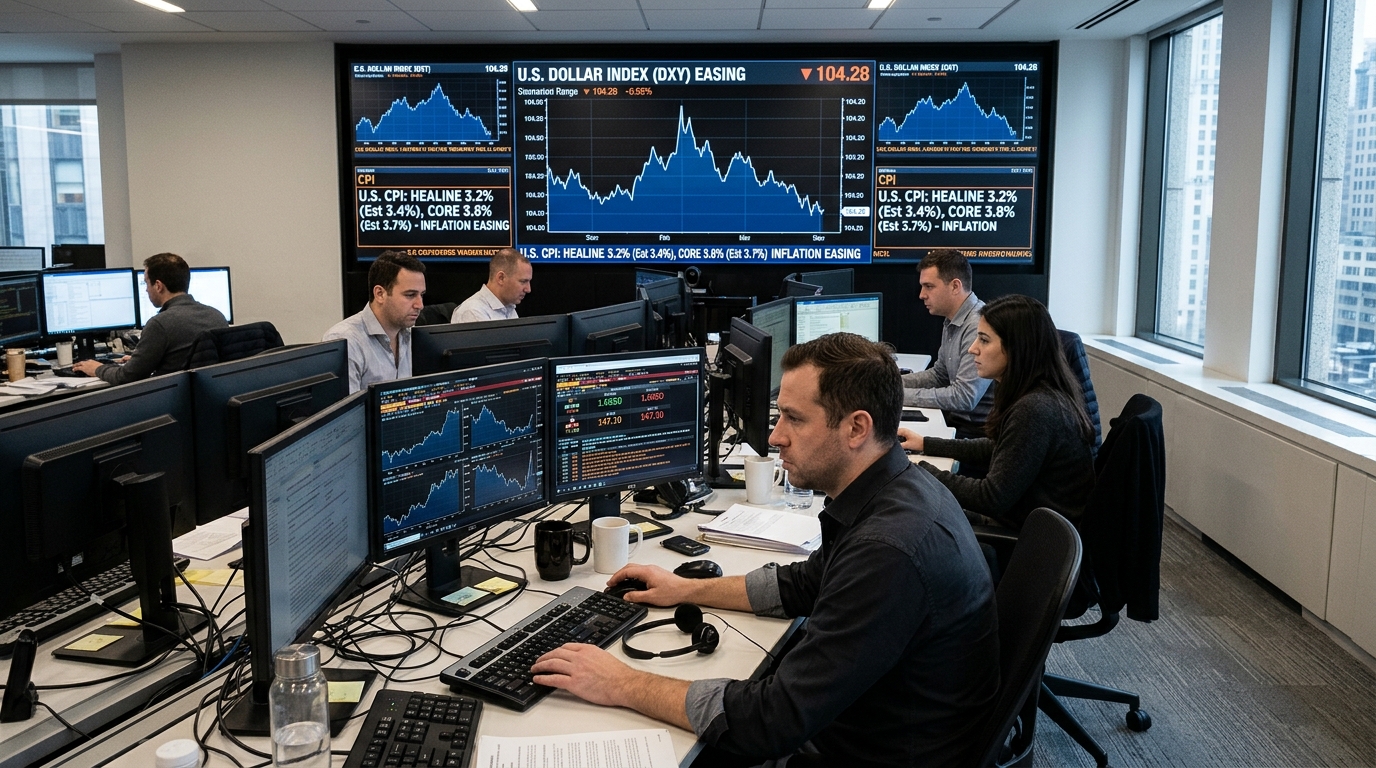
The U.S. dollar retreated from an earlier surge as currency markets shifted their focus from the recent jobs-driven move to the next major inflation test. According to an Investing.com report, the greenback eased after a post-payrolls jump as traders prepared for upcoming U.S. consumer price index data.
That sequence matters for global markets because it shows how quickly foreign-exchange pricing can pivot. A strong labor-market signal can push investors toward expectations of tighter policy or a longer period of elevated rates, supporting the dollar. But inflation data often acts as the next filter: if price pressures cool, the case for additional hawkishness can weaken; if inflation stays firm, the dollar could regain momentum.
Why CPI is now the main market driver
The dollar’s initial rise following labor-market strength suggested investors were reassessing the path of U.S. interest rates. In broad terms, stronger economic data can raise the probability that the Federal Reserve keeps policy restrictive for longer. That tends to support U.S. yields and the dollar against major peers.
Yet the next step in that logic depends heavily on inflation. The CPI release is important not just for the Fed, but for currency pairs across the board. It affects expectations for short-term rates, front-end bond yields and broader risk appetite. When markets are already sensitive to macro surprises, a single inflation print can reshape positioning in the dollar, euro, yen and emerging-market currencies.
This dynamic also fits with broader reader interest in cross-asset macro coverage. FX markets rarely move in isolation: a firmer or softer dollar can feed through to commodities, global equities and crypto sentiment.
A stronger dollar has wider market consequences
Even a modest dollar reversal can matter because the U.S. currency remains central to global pricing. A stronger dollar can tighten financial conditions internationally, particularly for economies and companies with dollar-linked borrowing. It can also weigh on commodity prices by making dollar-denominated assets more expensive for non-U.S. buyers.
By contrast, a softer dollar can offer short-term relief to risk assets and to some emerging markets. That does not guarantee a sustained trend, but it helps explain why traders are treating the inflation release as more than just a domestic U.S. event.
The move is especially relevant after a period when markets have had to digest multiple overlapping macro themes, including tariff tensions, geopolitical risk and mixed signals from major economies. The FX market’s shift from payrolls to CPI reflects an environment where conviction remains conditional rather than firm.
What traders may watch in the inflation data
While the Investing.com headline points to broad caution ahead of CPI, the market usually looks beyond the top-line number. Investors tend to monitor:
- Whether inflation is cooling or reaccelerating relative to recent trends
- The likely effect on Federal Reserve expectations
- How Treasury yields respond, especially at the short end
- Whether the dollar’s pullback broadens or reverses quickly after the release
Currency markets can be particularly sensitive when positioning is stretched after a sharp move. If traders had chased the dollar higher on labor-market strength, a softer-than-expected inflation reading could trigger profit-taking. If inflation surprises on the upside, the earlier dollar rally may find fresh support.
Why this matters globally
For global investors, the dollar remains one of the clearest transmission channels between U.S. data and international asset prices. Movements in the greenback affect import costs, capital flows and relative returns across markets. That is one reason a pullback ahead of CPI can become a notable story even without a major policy announcement.
The setup also highlights the current macro hierarchy: labor data may shape the first reaction, but inflation often delivers the stronger policy signal. Until that signal is clearer, FX markets may remain prone to short, event-driven reversals rather than durable trends.
Neutral outlook: The dollar’s retreat, according to Investing.com, suggests traders are unwilling to extend the post-jobs move aggressively before CPI. The inflation reading is likely to be the next key test for rate expectations and near-term FX direction.
MarketPro reports are AI-assisted analyses of publicly reported market news. Not investment advice.