US PPI Jumps 6.3%, Complicating Rates and Dollar Outlook
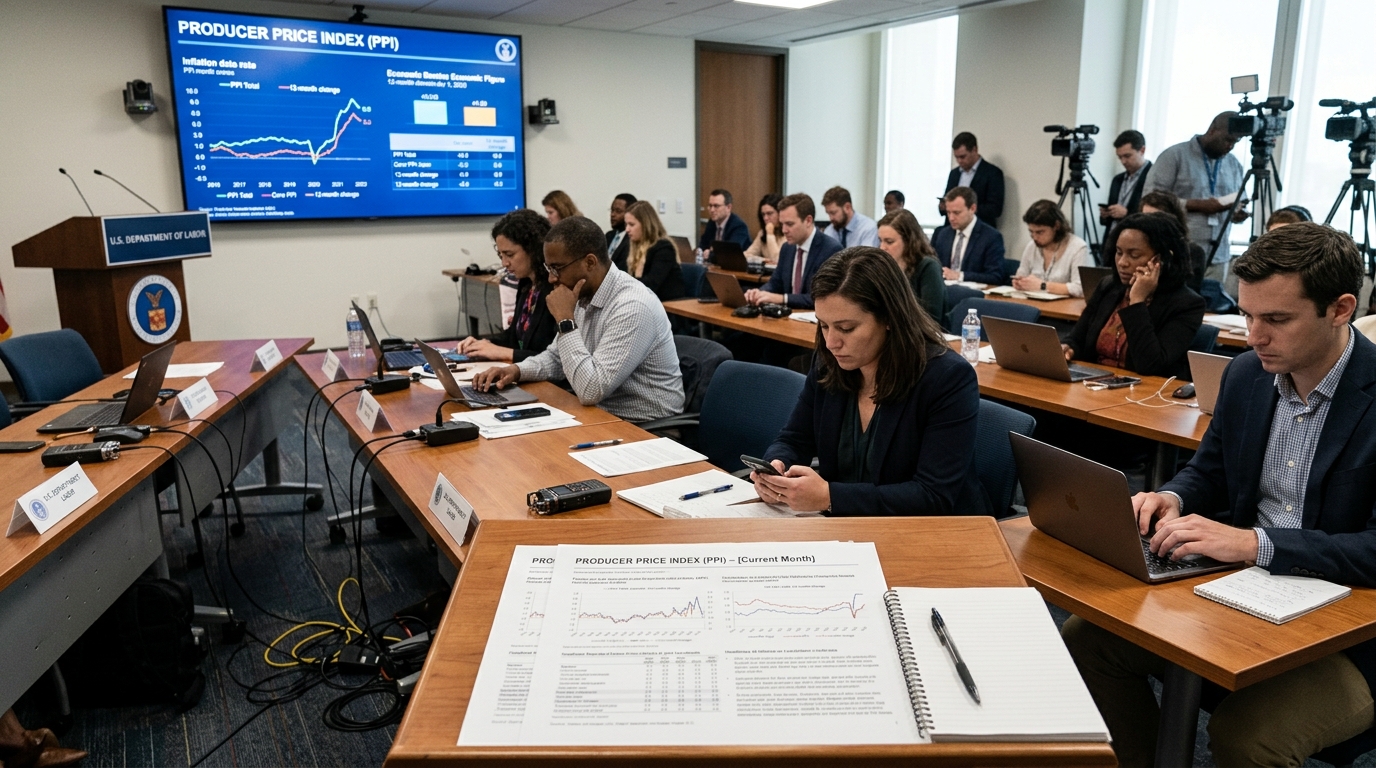
U.S. wholesale inflation accelerated sharply in September, with producer prices rising 6.3% from a year earlier, according to a CNBC report. The reading was described by CNBC as the biggest annual gain since 2022, putting fresh focus on inflation pressures that markets had already been struggling to assess.
The move matters beyond the headline. Producer prices are closely watched because they can signal pipeline inflation that may later affect consumer prices, corporate margins and monetary-policy expectations. A hotter PPI reading can reinforce concerns that inflation is proving broader and more persistent than investors had hoped.
Why the PPI report matters now
The September data arrives at a delicate time for global markets. CNBC separately reported that Treasury yields slid as investors moved into bonds during a technology-led sell-off. That combination is notable: markets are simultaneously dealing with growth and risk concerns on one side, and inflation pressure on the other.
Normally, stronger inflation can push yields higher if investors think the Federal Reserve may need to keep policy tighter for longer. But when equity markets are under stress, demand for safe-haven government debt can pull yields lower in the short term. That leaves investors balancing two competing forces: inflation risk and a flight to safety.
CNBC also reported that the U.S. Treasury dismissed an IMF warning on debt and criticized what it called messy forecasting. While that is a separate policy debate, it connects to the market backdrop because inflation, deficits and borrowing costs are increasingly being discussed together by investors.
Potential implications for rates, margins and the dollar
A strong producer inflation reading can matter for several asset classes at once:
- Rates: It may reduce confidence that inflation is cooling smoothly.
- Equities: Companies may face more pressure if higher input costs cannot be fully passed on to customers.
- Foreign exchange: Persistent inflation can affect expectations for U.S. interest rates, a key driver for the dollar.
- Bonds: Investors may need to weigh whether safe-haven demand or inflation expectations are the bigger immediate force.
MarketWatch has also highlighted a longer-run rates concern from another angle, reporting that signs point to mortgage rates staying above 7% in 2027. That is not a direct follow-through from the September PPI report, but it underscores how sticky inflation and elevated borrowing costs remain central to the broader macro narrative.
What investors will watch next
The September PPI figure on its own does not settle the policy outlook, but it raises the stakes for upcoming inflation and labor-market data. Investors will also watch whether companies begin to talk more openly about input-cost pressure during earnings season, especially in sectors with thinner margins or less pricing power.
For currency markets, the key question is whether the latest inflation data changes expectations for U.S. policy enough to influence the dollar’s path. For bond markets, the issue is whether inflation pressure reasserts itself after the latest safe-haven bid.
According to CNBC reports, markets are already navigating a difficult mix of inflation concern, deficit anxiety and risk-off trading. The stronger PPI reading adds another layer to that picture rather than resolving it.
Neutral outlook
The September wholesale inflation jump strengthens the case that inflation remains a live market risk. The next moves in yields, the dollar and equities will likely depend on whether this report proves to be an isolated spike or part of a broader trend.
MarketPro reports are AI-assisted analyses of publicly reported market news. Not investment advice.