U.S. GDP Growth Beats Forecasts as Inflation Stays Firm
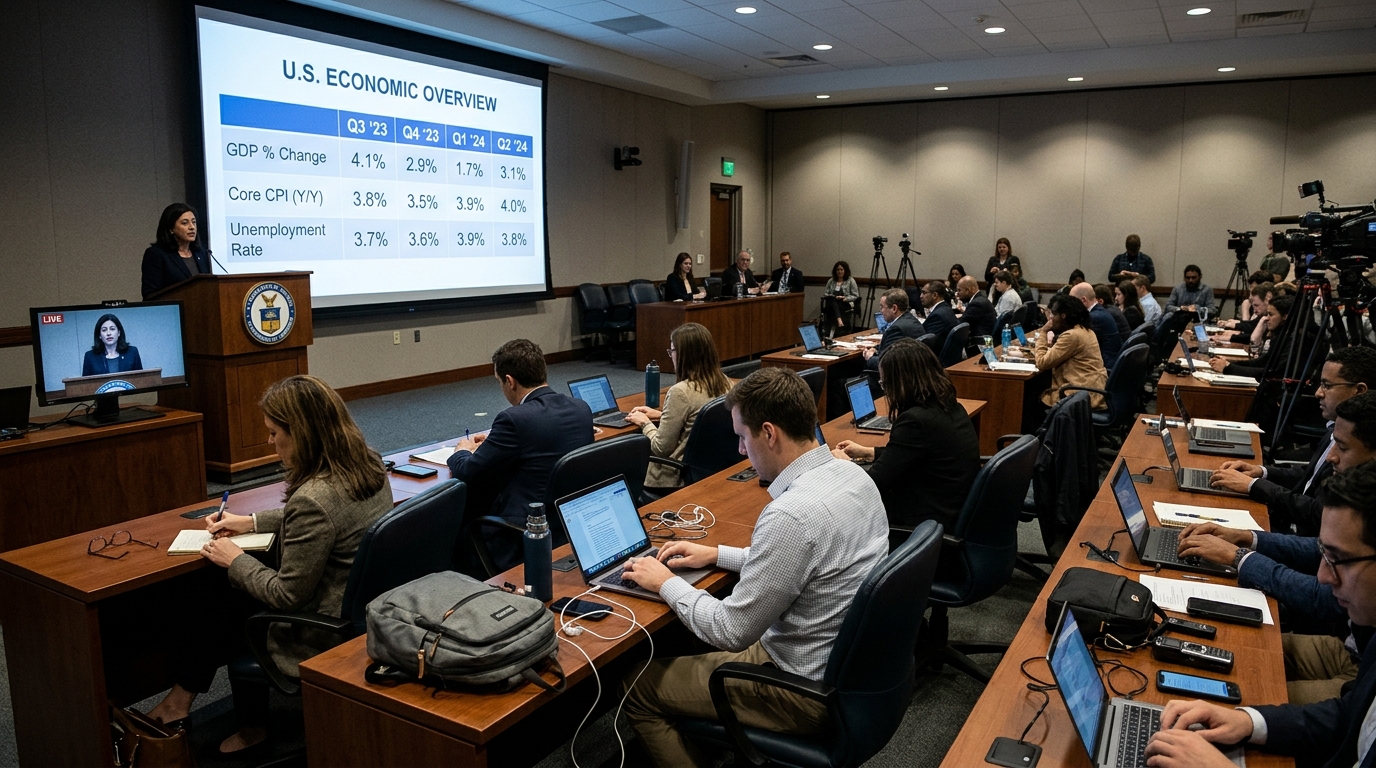
The U.S. economy expanded at a faster-than-expected 3.4% annualized pace in the third quarter, according to a CNBC report, while September inflation accelerated. MarketWatch also reported that the economy grew at its fastest pace in a year and showed little sign of slowing, reinforcing the view that growth has remained resilient even as borrowing costs stay elevated.
Taken together, the headlines point to a familiar but still market-moving combination: stronger output growth paired with inflation that has not fully cooled. For investors and policymakers, that mix matters because it can keep interest-rate expectations higher for longer, even if growth itself looks healthy on the surface.
Growth resilience meets sticky price pressure
According to CNBC, the third-quarter GDP reading beat expectations, signaling that household demand and broader economic activity have remained firmer than many anticipated. MarketWatch’s coverage added that the report showed little sign of a meaningful slowdown, underscoring that the economy has continued to absorb higher financing costs better than expected.
But the same CNBC headline also noted that September inflation accelerated. MarketWatch separately reported that consumer spending flattened out after the inflation surge, suggesting that momentum may be holding up at the aggregate level even as households become more selective.
That tension is central for markets. Strong GDP on its own can support risk appetite and corporate revenue expectations. However, when inflation also firms, the policy backdrop becomes more complicated. A still-expanding economy gives the Federal Reserve less urgency to ease financial conditions quickly, especially if price pressures are not clearly moving lower.
Why cross-asset markets care
The immediate significance of a stronger GDP reading is not limited to economic optics. It can influence Treasury yields, the U.S. dollar and equity sector performance, particularly in rate-sensitive areas such as housing, small caps and consumer discretionary shares.
According to MarketWatch, the cost of money remains a central issue for households dealing with expensive car loans, mortgages and credit-card balances. That helps explain why a hot growth print may not translate neatly into broad-based optimism: higher-for-longer rates can support bank margins and the dollar, but they can also pressure consumers and interest-rate-sensitive industries.
Reader interest on MarketPro has consistently favored stories that connect macro data to multiple asset classes. This GDP report fits that pattern because it speaks not just to growth, but to the likely path of rates, bond-market pricing, currency strength and corporate demand conditions.
Consumer and housing signals remain mixed
There were also signs elsewhere in the wire that the consumer picture is becoming more uneven. CNBC reported that home prices fell and rents rose for the first time in three years, while MarketWatch said consumer spending flattened after the inflation surge. Those developments do not contradict the GDP strength, but they do suggest that headline resilience may be masking growing pressure beneath the surface.
Housing and household consumption remain among the most interest-rate-sensitive parts of the economy. If inflation stays firm, financing conditions may remain restrictive, limiting how much stronger growth can spread through the broader economy.
That is especially relevant for markets trying to judge whether growth is re-accelerating sustainably or simply proving sticky enough to delay an easier policy backdrop.
What the GDP report changes — and what it does not
The latest data strengthens the case that the U.S. economy is not rolling over. According to CNBC and MarketWatch, growth has beaten expectations and remains robust by recent standards. At the same time, inflation acceleration means the report is unlikely to be read as an all-clear signal for lower rates.
For global markets, that combination tends to have broad spillovers. It can support the dollar, keep bond yields sensitive to incoming inflation data, and complicate the outlook for equities that depend on cheaper capital. It also raises the bar for sectors and regions hoping for a rapid easing in U.S. financial conditions.
Neutral outlook: The GDP surprise strengthens the narrative of U.S. economic resilience, but the accompanying inflation signal means markets are still likely to trade on the balance between solid growth and persistent price pressure.
MarketPro reports are AI-assisted analyses of publicly reported market news. Not investment advice.