Global Markets Daily Brief — October 02, 2026
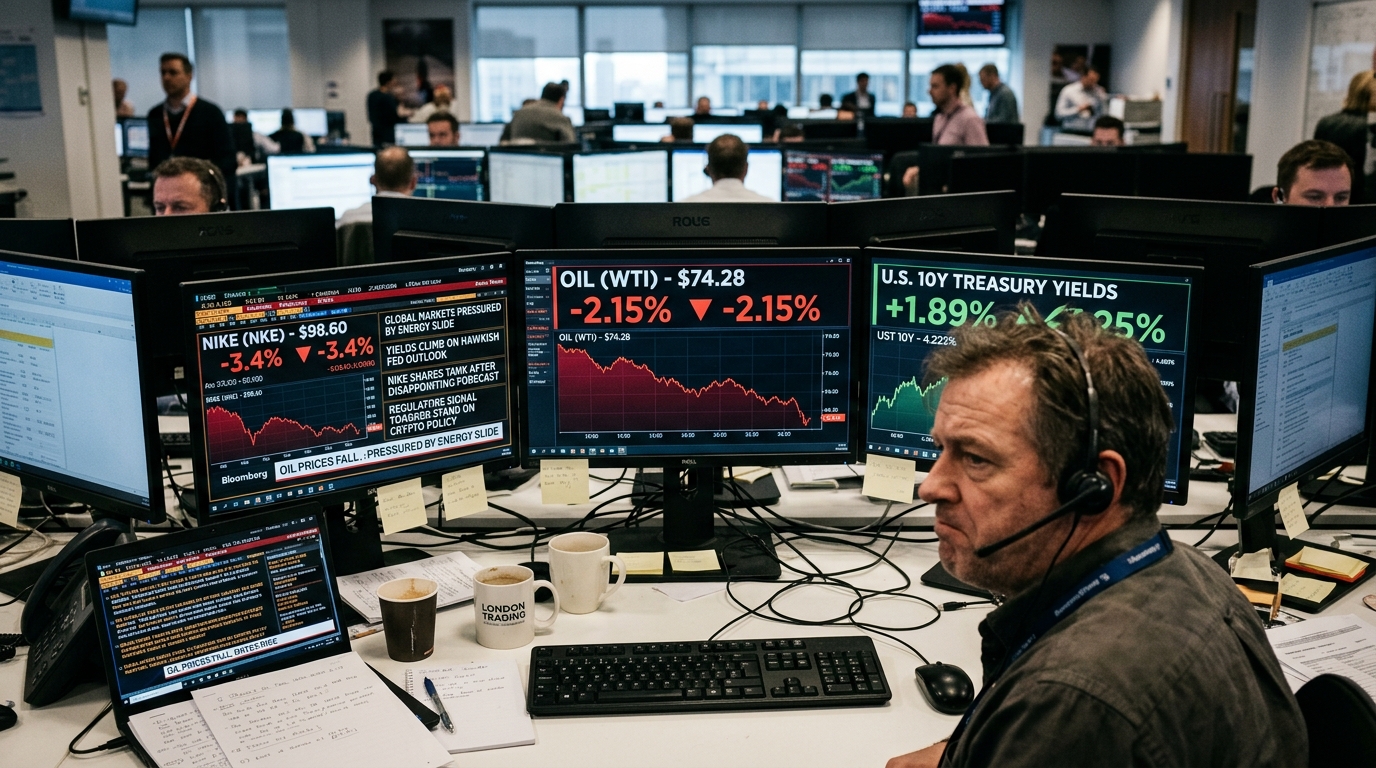
Global markets opened October 2 with investors balancing a sharp retreat in oil, slightly firmer U.S. bond yields, renewed geopolitical risk in the Middle East and another burst of crypto-policy headlines from Washington and Asia.
The broad picture is one of cross-currents rather than a single dominant theme. According to CNBC, oil prices fell more than 3% after a report that a potential release of diesel and crude stocks could ease near-term supply pressure, pulling Brent back below $100. At the same time, CNBC also reported that the United States will send a third carrier group to the Middle East as President Donald Trump warned of possible new strikes on Iran, underscoring that geopolitical risk remains elevated even as crude prices moved lower.
Energy falls despite geopolitical tension
That combination is unusual but not unprecedented. Commodity markets often react first to immediate supply signals, and the report of a possible stock release appears to have outweighed the security premium that had recently lifted crude. The move back below $100 for Brent, as reported by CNBC, matters beyond the energy complex because it may relieve some inflation pressure if sustained.
For equity investors, lower oil can support transport, consumer and industrial sectors, though the benefit may be tempered by the uncertainty created by rising military tension in the region. The fact that both developments arrived at once left traders reassessing whether energy markets are being driven more by emergency policy tools or by conflict risk.
Rates and policy remain central
In fixed income, CNBC said Treasury yields inched higher as investors awaited a key jobs report. That keeps labor-market data at the center of the macro narrative. A firmer yield backdrop can tighten financial conditions, pressure rate-sensitive stocks and strengthen the dollar, although the day’s headlines did not provide a separate broad dollar move to confirm that path.
U.S. policy uncertainty also remained in focus on several fronts. CNBC reported that Washington’s major crypto bill is stuck, while the Securities and Exchange Commission is continuing to push ahead. Separately, Cointelegraph reported that the SEC is moving to clear a custody hurdle for advisers offering crypto. Taken together, those reports point to a market environment in which agency action may keep shaping digital-asset access even without a major legislative breakthrough.
Stocks: consumer and tech angles diverge
In equities, CNBC reported that Nike shares fell after disappointing sales and a layoff announcement tied to restructuring. MarketWatch also highlighted that this could be the company’s worst year ever in the stock market, with sales expected to decline further. With both outlets pointing to the same underlying pressure, Nike stands out as one of the day’s clearest company-specific setbacks.
Elsewhere in technology infrastructure, MarketWatch reported that Amazon is raising chip-rental prices and is reportedly moving Nvidia processors off the balance sheet. While the details still appear tied to a single report, the headline signals continued cost and capital-discipline questions around the AI buildout.
Crypto and Asia add to the policy mix
Crypto markets saw supportive flow data alongside regulatory movement. Cointelegraph reported that Bitcoin ETFs began October with a $103 million inflow. That follows earlier strong reader interest in crypto market-structure stories, but today’s more consequential development may be regulatory rather than price-led.
In Asia, Cointelegraph said South Korea is advancing tokenized securities rules ahead of a 2027 rollout, while also reporting that exchange profits in the country fell sharply in the first half amid a trading slump. The contrast is notable: weaker trading activity today, but continued institutional rulemaking for future market infrastructure.
Trade and geopolitics stay in the background
Beyond markets, CNBC reported that U.S. Trade Representative Greer said a deal with India is not “imminent” following a Modi-Trump call. That tempers expectations for a near-term trade breakthrough with one of the world’s largest growth markets.
Overall, the day’s market tone is defined by falling oil, slightly higher yields, regulatory momentum in crypto and selective equity stress led by Nike. Neutral outlook: the next major signals for cross-asset markets are likely to come from U.S. jobs data, any confirmation around energy stock releases and whether crypto policy advances through regulators or lawmakers first.
MarketPro reports are AI-assisted analyses of publicly reported market news. Not investment advice.