Global Markets Daily Brief — October 03, 2026
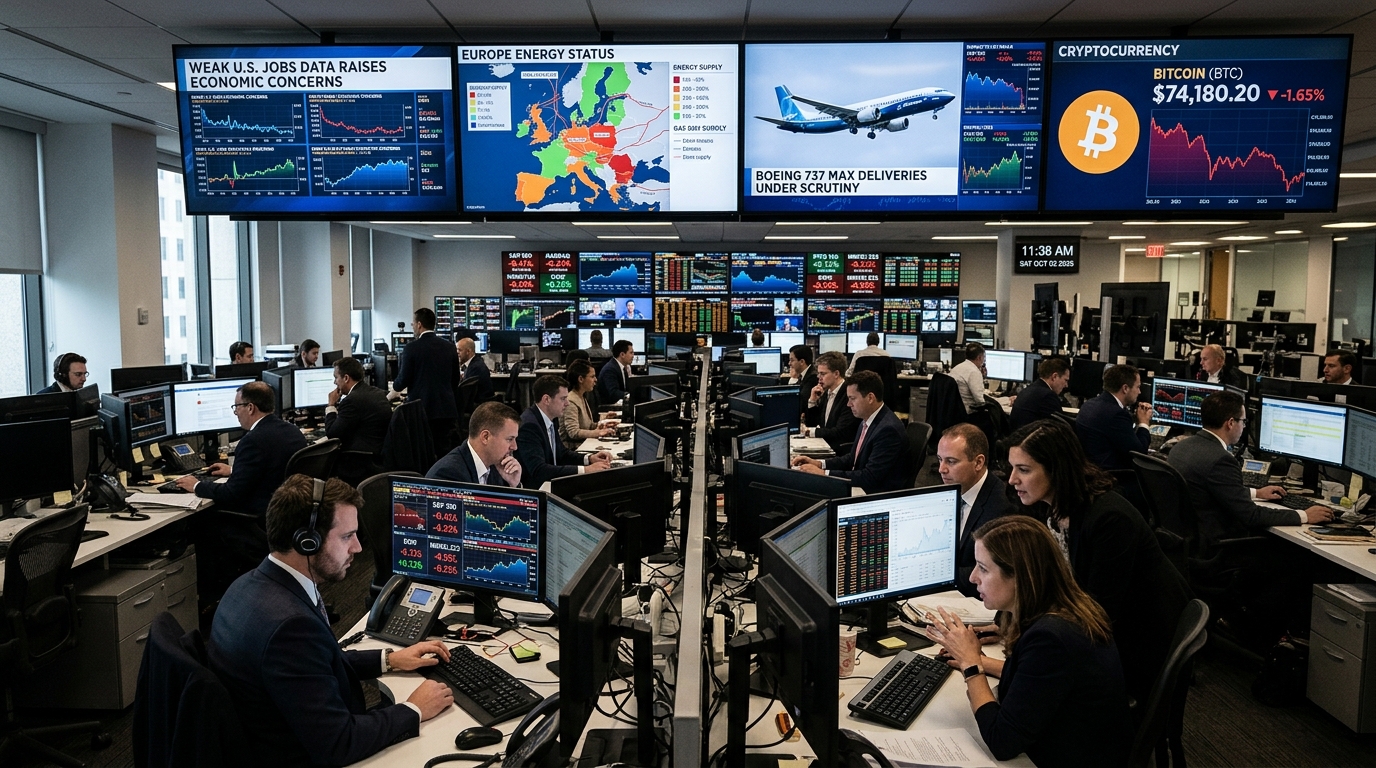
Global markets entered the new session with several cross-asset themes competing for attention: a sharply weaker-than-expected U.S. labor report, emergency moves to ease diesel supply pressure, fresh headlines around aerospace and artificial intelligence, and renewed volatility in crypto.
According to CNBC, U.S. payroll growth slowed dramatically in September, with just 29,000 jobs added and the unemployment rate rising to 4.2%. Cointelegraph separately reported that Bitcoin briefly touched $87,000 as weak U.S. jobs data pushed bond yields lower, underscoring how quickly macro data can spill into digital assets as well as traditional markets.
Macro picture turns softer
The labor market slowdown was the day’s clearest macro signal. CNBC also published a separate analysis saying men are losing ground in the labor market, suggesting the weakness may not be evenly distributed across sectors and demographics. Even without broader cross-confirmation in the provided wires, the combination of a weak payrolls headline and labor-market structural analysis points to a softer U.S. growth backdrop.
That matters for multiple asset classes at once. A weaker labor market can affect expectations for consumer demand, business investment and interest-rate policy. It also helps explain why risk sentiment looked uneven rather than uniformly negative: softer growth data can pressure cyclical assets while simultaneously lowering yields and supporting rate-sensitive trades.
Energy stress remains a live issue
Fuel markets were another major focus. CNBC reported that G7 nations will release diesel stocks as wars in Europe and the Middle East constrain fuel supplies. MarketWatch separately reported that Europe’s leaders are rushing to release diesel from stockpiles as a fuel shock hangs over the U.S. political backdrop. Taken together, those reports suggest policymakers are treating diesel tightness as a real supply problem rather than a short-lived dislocation.
The cross-market relevance is significant. Diesel is central to freight, industry and agriculture, so supply stress can feed through to transportation costs and broader inflation expectations. The policy response also shows that governments are prepared to use strategic inventories when geopolitical disruptions start affecting refined-product markets directly.
Corporate news sends mixed signals
In equities, the tone was mixed across sectors. CNBC reported that Ford held onto the No. 3 U.S. sales position in the third quarter, fending off Hyundai, while MarketWatch said Tesla sold far more EVs than Wall Street expected, lifting its stock. Those two stories point to continued competitive intensity in autos, with legacy manufacturers defending share even as EV demand remains a key market narrative.
Aerospace also stayed in focus. CNBC reported that the FAA said a Boeing 737 Max software glitch is not a flight-safety issue. That distinction matters because safety-related headlines can quickly spill into airline, supplier and industrial sentiment. The FAA framing may help limit broader market fallout, even if the issue still draws scrutiny.
Elsewhere in tech, CNBC reported that Cerebras shares fell to a post-IPO low, dropping 20% for the week amid Nvidia pressure and a lockup expiration. That headline fits a wider pattern in AI-linked equities: investor enthusiasm remains strong for the theme overall, but valuation sensitivity and competitive pressure are still reshaping individual winners and losers.
AI and crypto keep evolving
Artificial intelligence remained prominent beyond listed equities. CNBC reported that Anthropic plans to invest $100 million to train AI engineering talent. MarketWatch also highlighted a clash involving Anthropic and Pope Leo over whether AI has a soul, though that piece is more conceptual than market-moving. The capital commitment itself is the clearer economic signal, showing that competition in AI is extending beyond chips and models into labor supply and training pipelines.
Crypto headlines, meanwhile, pointed to both price momentum and infrastructure strain. Cointelegraph reported Anchorage Digital is cutting 17% of its workforce, while another report said Blast will wind down its Ethereum layer-2 network after costs outpaced revenue. Those developments suggest that even as token prices rally, parts of crypto market plumbing remain under pressure.
Short neutral outlook
The market picture is mixed but coherent: softer U.S. labor data is colliding with energy supply concerns, while company-specific news in autos, aerospace, AI and crypto continues to drive dispersion. Near term, investors are likely to keep watching whether macro weakness, diesel interventions and crypto price moves reinforce or offset one another.
MarketPro reports are AI-assisted analyses of publicly reported market news. Not investment advice.