Global Markets Daily Brief — October 23, 2026
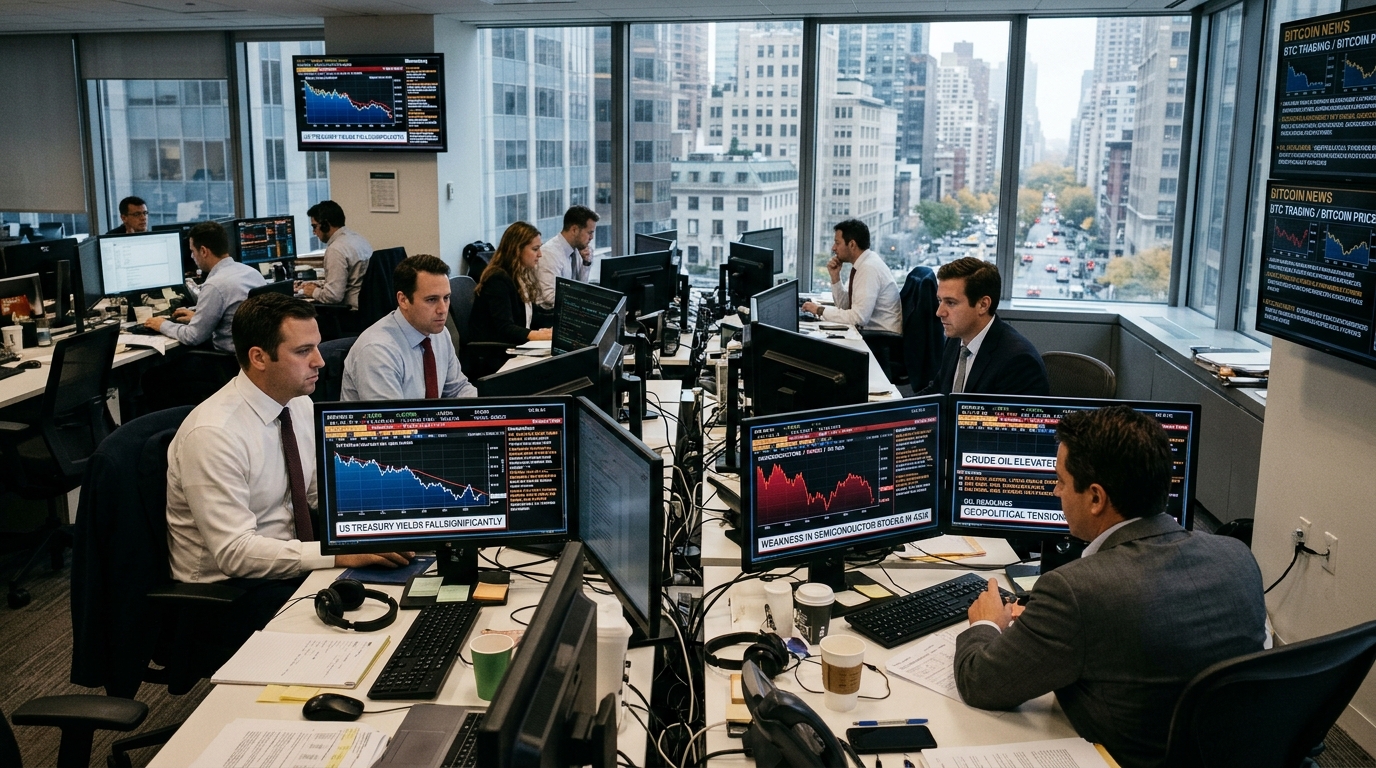
Global markets on October 23 were shaped by a clear shift toward risk reassessment across rates, equities, commodities and crypto. The broad picture from the day’s wire headlines was a market balancing lower bond yields against renewed stress in parts of the technology complex, while energy and digital-asset stories added to a still uneven cross-asset backdrop.
The biggest macro signal came from the U.S. rates market. CNBC reported that the 10-year Treasury yield fell below 5% to its lowest level in nearly a month. MarketWatch separately said Treasury yields logged their biggest drop since the 2023 banking crisis. Taken together, those reports point to a meaningful move in the world’s benchmark bond market, one that tends to ripple across equity valuations, the dollar and broader risk appetite.
Lower yields can support growth assets in theory, but Thursday’s headlines showed that equity investors were still discriminating sharply between sectors and even among individual names. Semiconductor and AI-related stocks were under pressure after CNBC reported that SK Hynix shares slid following the company’s decision to scrap plans for a Solidigm initial public offering. Investing.com also highlighted the decline in SK Hynix and separately flagged weakness in Samsung Electronics, while MarketWatch pointed to broader pressure on Micron and other chip stocks.
Rates relief meets selective equity stress
That mix matters because it suggests lower yields alone were not enough to offset company-specific and sector-specific concerns. In chips, investors appeared to be reassessing demand expectations, capital needs and listing-related sentiment. In big tech, CNBC reported that Meta shares fell nearly 7% as AI spending pushed free cash flow negative, reinforcing how capital intensity remains a central market issue even when bond yields retreat.
Healthcare added another example of fragile sentiment. Although this particular story has already been separately covered by MarketPro and is not being revisited as a standalone feature here, the day’s wires still showed how biotech gains can be overshadowed by disclosure and timing concerns.
Outside equities, the commodity backdrop remained tense. MarketWatch reported that oil prices were approaching Iran-war highs as tanker rates surged, while Investing.com said oil was little changed but supply concerns lingered amid Houthi attacks on Saudi Arabia. Those headlines suggest that even without a fresh price spike on the day, the energy market remains sensitive to transport disruption and regional security risks.
Crypto and policy remain active themes
Crypto markets also saw policy and product developments that could matter beyond digital assets alone. Cointelegraph reported that Switzerland approved what it described as the first spot Bitcoin ETF for retail investors, a notable headline for European crypto access if confirmed more broadly by regulators and issuers in coming days. In the U.S., Cointelegraph also reported that the Pentagon banned U.S. forces from using military information to bet in prediction markets, underlining how digital-market oversight is widening into adjacent sectors.
Meanwhile, blockchain data infrastructure continued to expand, with Cointelegraph reporting that Dune launched real-time feeds covering 200 onchain trading venues. While niche on the surface, such developments speak to a larger institutionalization trend across market data and alternative trading ecosystems.
What the cross-asset picture suggests
For global investors, the day’s pattern was less about a single dominant narrative and more about fragmentation:
- Bonds: a sharp rally lowered yields and may ease some valuation pressure.
- Stocks: chips and selected tech names remained vulnerable to execution and spending concerns.
- Commodities: oil stayed supported by geopolitical and shipping risks.
- Crypto: regulation, access products and market plumbing continued to evolve.
MarketWatch described the U.S. stock market as fracturing into two camps, and that framing fits the broader tape. Some assets are responding to falling yields as a relief signal, while others remain tied to earnings quality, capital discipline and geopolitical exposure.
A separate political note may also matter at the margin for sentiment. CNBC reported that President Donald Trump’s approval rating on the economy hit an all-time low in a CNBC survey as the midterm backdrop builds. That does not immediately change asset pricing, but it can sharpen attention on policy messaging, fiscal expectations and election-linked volatility.
Neutral outlook: the next key test is whether the bond rally broadens into sustained support for risk assets, or whether sector-specific pressures in chips, big tech and energy-sensitive areas keep markets divided.
MarketPro reports are AI-assisted analyses of publicly reported market news. Not investment advice.