Global Markets Daily Brief — October 29, 2026
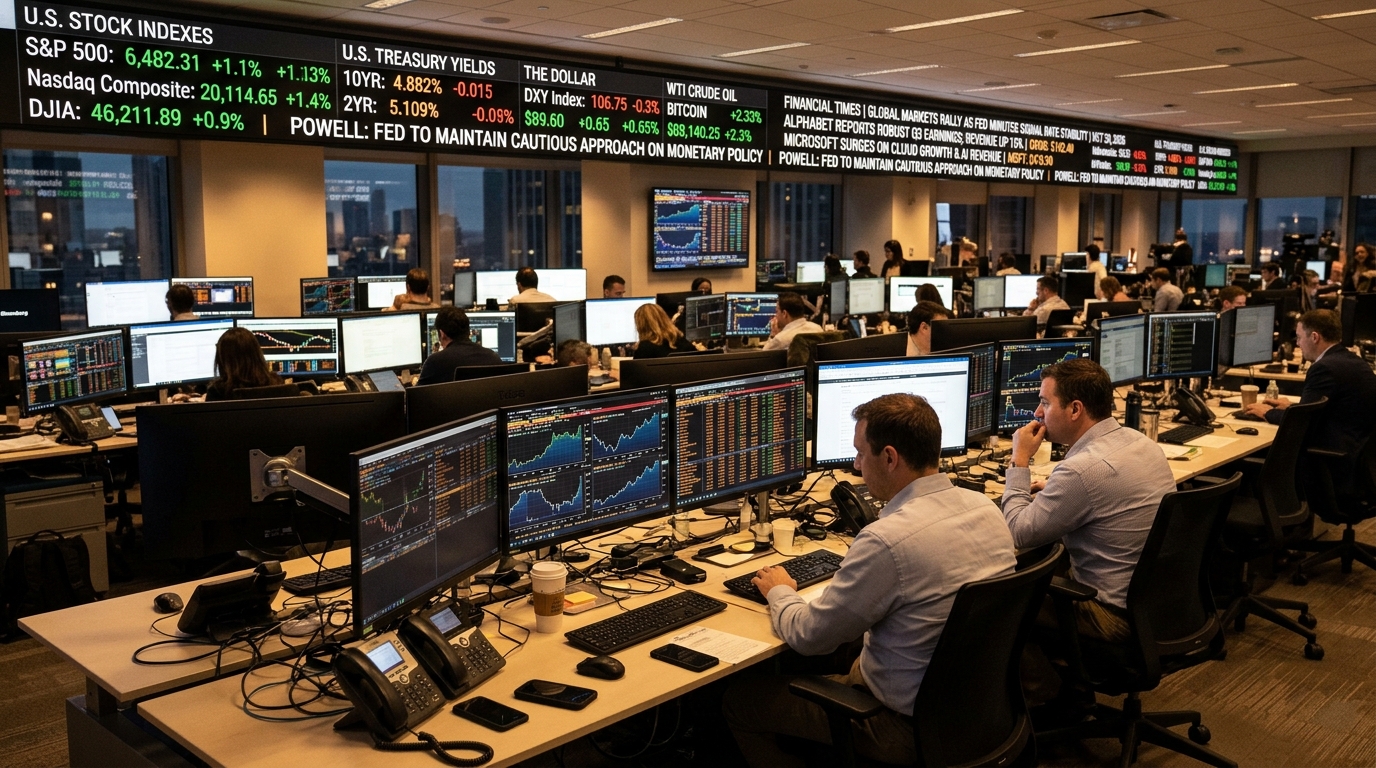
Global markets traded through a mix of central-bank caution, uneven technology earnings and softer oil prices on October 29. Based on the day’s wire headlines, investors were balancing a steady Federal Reserve, higher long-dated Treasury yields, diverging reactions to major U.S. tech results, pressure in parts of Asia’s equity market and a cautious tone across crypto.
According to CNBC, the Federal Reserve kept rates unchanged, while the 10-year Treasury yield moved higher even after the decision. Investing.com separately reported that the U.S. dollar was steady after the Fed hold left the rate path murky. In crypto, Cointelegraph said analysts saw the Fed’s hawkish hold as continuing to pressure bitcoin.
In equities, the day was defined by sharp stock-specific moves with broader thematic implications. CNBC reported that Microsoft rose after cloud growth helped drive an earnings and revenue beat, while Alphabet fell 10% after holding 2026 capital expenditure unchanged and signaling a significant increase in 2027. MarketWatch also highlighted Microsoft’s post-earnings advance and warned that Alphabet could be facing one of its worst drops in years after its latest results, giving added cross-source support to those moves.
That split in the AI trade spilled into related names. CNBC reported that CoreWeave and other neocloud stocks dropped after Microsoft capital expenditure came in below some investors’ expectations. The reaction suggests that even when a megacap earnings report is broadly well received, markets are still highly sensitive to spending signals around AI infrastructure.
Asia added another layer of caution. CNBC said Samsung Electronics shares slid despite record third-quarter profit, while it also reported that China’s technology favorites were losing momentum in a broader sell-off. Investing.com separately asked why Samsung Electronics stock was sliding, reinforcing that the company’s share move was a significant regional market talking point.
In commodities, the tone was softer. Investing.com reported that oil prices fell as hopes for peace offset fears of a widening Middle East conflict. That move stood out because it came even as geopolitical risk remained in focus, underscoring how quickly oil can reprice when traders see even tentative signs of de-escalation.
Crypto remained under pressure from the same macro backdrop affecting rates and the dollar. Cointelegraph reported that bitcoin’s bounce was rejected at its 50-day trend line ahead of the Fed and earnings, and later said the Fed’s hawkish pause kept pressure on the token. Those headlines point to a market still trading in line with broader liquidity expectations rather than on crypto-specific optimism.
What moved markets
- Fed policy: Rates were left unchanged, but the tone was cautious enough to keep markets debating whether policy is restrictive enough.
- Bond market: The 10-year Treasury yield edged higher, signaling that longer-term rate expectations remain a live issue.
- Big Tech: Microsoft’s results supported parts of the AI story, while Alphabet’s capex message triggered a sharp repricing.
- Asia tech: Samsung and Chinese tech names showed that strong headline profits are not always enough to lift sentiment.
- Oil and crypto: Oil weakened on peace hopes, while bitcoin stayed sensitive to the Fed backdrop.
Cross-asset picture
The clearest message from the session was that markets are still trading through a macro filter. Stocks reacted not just to earnings, but to what those earnings implied for future investment and demand. Bonds and the dollar reflected uncertainty over the next phase of Fed policy. Oil responded to geopolitical headlines rather than growth optimism. Crypto remained tied to interest-rate expectations.
For readers tracking the bigger picture, October 29 looked less like a broad risk-on or risk-off day and more like a selective repricing across asset classes. Investors rewarded visible earnings strength and punished ambiguity around spending, while keeping a close eye on the path of rates and global risk sentiment.
Neutral outlook: The next market cues appear likely to come from whether Treasury yields keep rising, whether Big Tech spending signals stabilize sentiment in AI-linked shares, and whether the dollar, oil and bitcoin continue to reflect a cautious post-Fed tone.
MarketPro reports are AI-assisted analyses of publicly reported market news. Not investment advice.