US jobs growth cools sharply as unemployment ticks up
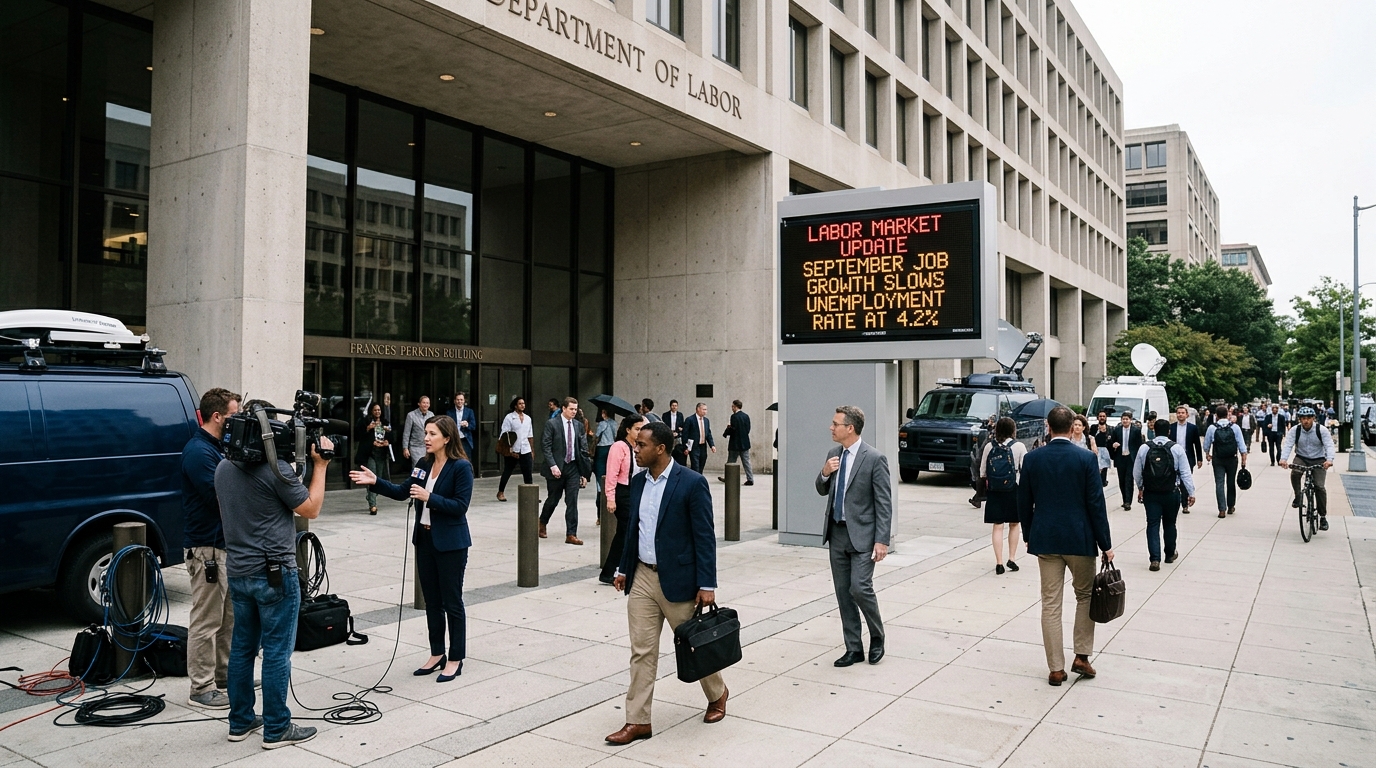
U.S. labor-market momentum weakened markedly in September, with payroll growth slowing to just 29,000 and the unemployment rate rising to 4.2%, according to a CNBC report citing the latest jobs data. For global markets, the report adds a fresh macro signal at a time when investors are already balancing questions around growth, interest rates and risk appetite.
Even without additional figures from other wire sources in today’s headline set, the combination of very modest job creation and a higher unemployment rate is significant on its face. Labor-market conditions have been one of the key pillars supporting the broader U.S. economy. A softer reading therefore matters well beyond domestic employment trends, because it can influence expectations for monetary policy, Treasury yields, the dollar and equity-sector leadership.
Why the September reading matters
A gain of 29,000 jobs is a sharp slowdown in headline hiring by historical standards. The move higher in the unemployment rate to 4.2% reinforces the idea that labor demand may be cooling rather than merely normalizing. According to CNBC, that combination defined the September report.
Markets typically treat labor data as one of the most important high-frequency readings on the health of the U.S. economy. Strong employment can support consumer spending and corporate earnings, while weaker hiring can raise concerns about future demand. At the same time, softer jobs data can also reduce pressure on the Federal Reserve if investors conclude that labor-market tightness is easing.
That creates a familiar two-sided market interpretation. On one hand, weaker jobs growth may be read as a warning that economic momentum is slowing. On the other, it may strengthen the case for a less restrictive policy path if inflation pressures are no longer being reinforced by an exceptionally tight labor market.
Implications for rates, the dollar and equities
The labor report arrives at a moment when macro investors remain highly sensitive to any data that could shift the interest-rate outlook. Employment data often feeds directly into pricing across government bonds and foreign-exchange markets, because it affects expectations for how long policy rates may stay elevated.
If investors interpret the September report as evidence of a broad-based cooling trend, the immediate consequence could be renewed focus on whether yields have further room to fall from recent highs or whether the Federal Reserve may gain flexibility. That matters for rate-sensitive sectors, including housing, consumer discretionary spending and smaller-cap equities.
For currency markets, a softer labor backdrop can also affect the dollar if traders judge that U.S. rate support may fade relative to other major economies. Today’s headline set does not include a separate forex confirmation tied directly to the jobs print, so the clearest conclusion supported by the available reporting is that the labor data raises the importance of upcoming policy communication and market reaction.
Why global investors are watching
The U.S. jobs market remains a global macro anchor. Slower hiring can shape sentiment across:
- Equities, through implications for earnings and consumer demand
- Bonds, through changing expectations for policy rates
- Currencies, through interest-rate differentials and growth outlooks
- Commodities, through revised assumptions about economic activity
That is especially relevant because investors have recently been navigating a market environment dominated by rates, oil and cross-asset volatility. A labor-market disappointment does not settle the debate over recession risk or the policy path, but it does add weight to the argument that growth may be losing some momentum.
What comes next
The next question for markets is whether September’s slowdown proves temporary or signals a more durable weakening trend. Investors will likely look for confirmation in future payroll reports, wage indicators, jobless-claims data and comments from Federal Reserve officials.
For now, according to CNBC, the headline message is straightforward: hiring slowed sharply in September and unemployment moved higher. That keeps the U.S. labor market at the center of the global macro narrative.
Neutral outlook: The September jobs report points to a cooler labor backdrop, but markets will need follow-through from upcoming data and policy signals before drawing firmer conclusions about the broader U.S. economy.
MarketPro reports are AI-assisted analyses of publicly reported market news. Not investment advice.