Tax Brackets for 2027 Reset Planning for U.S. Households
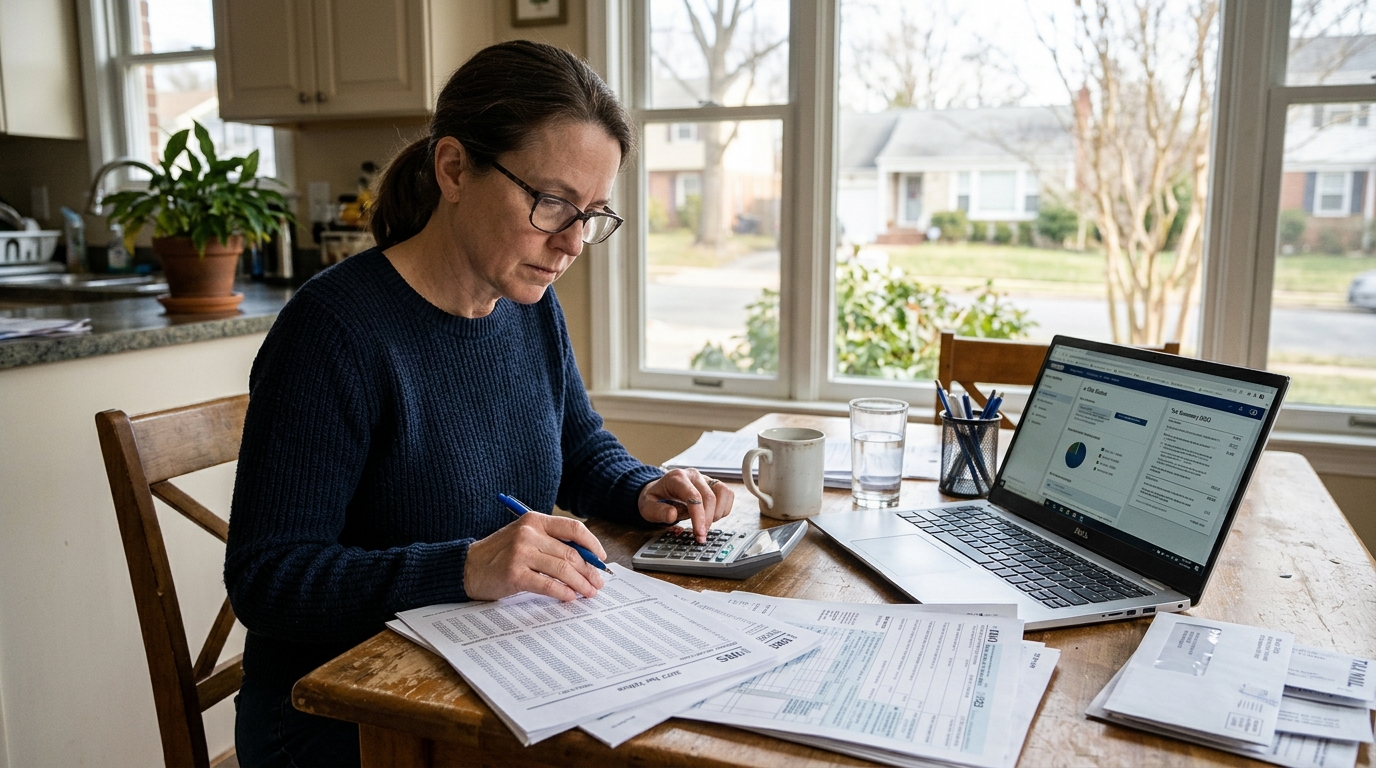
The Internal Revenue Service has released new federal income-tax brackets for 2027, giving U.S. households an updated benchmark for tax planning ahead. CNBC reported that the IRS announced the new brackets, while MarketWatch separately highlighted updated capital-gains rates, standard deductions and the implications for Roth conversions.
The release matters because annual bracket resets influence decisions on withholding, retirement withdrawals and gains realization. While tax-bracket updates are routine, the 2027 figures arrive at a time when households are paying closer attention to after-tax income, especially as market volatility has complicated portfolio and retirement planning.
What changed for 2027
According to CNBC, the IRS published the new federal income-tax brackets for 2027. MarketWatch said the update also includes revised capital-gains tax rates by income level, as well as changes to the standard deduction and state-and-local-tax treatment discussed in its tax coverage.
Neither development is a market shock on its own, but together they create a new framework for year-ahead financial decision-making. Tax brackets affect how quickly marginal tax rates rise as income increases. Capital-gains thresholds can influence the timing of asset sales. Standard deduction adjustments can alter the value of itemizing versus taking the flat deduction.
MarketWatch also focused on Roth conversion questions, noting that the new brackets may reshape how much some retirees and near-retirees choose to convert from traditional retirement accounts. That angle has become more relevant as older investors weigh future required withdrawals against current tax costs.
Why markets and households care
For investors, tax policy updates can subtly change behavior even without any change in the underlying economy. Higher or lower thresholds may encourage some households to realize gains sooner, defer income, or rebalance retirement assets differently. Those decisions can affect flows into taxable brokerage accounts, retirement vehicles and cash management products.
The 2027 schedule may be especially important for retirees and pre-retirees. Several of today’s MarketWatch headlines centered on households with large traditional IRA balances and questions around Roth conversions. That suggests tax-positioning remains a live issue for a broad segment of readers, particularly when market swings have made account values less predictable.
Tax changes can also affect consumer behavior. If households expect a modest change in take-home pay or tax liability, they may adjust savings, charitable giving or spending plans. The effect is usually gradual rather than immediate, but in aggregate it matters for sectors tied to discretionary consumption and wealth management.
What advisers will watch next
Wealth managers, accountants and payroll departments will now be reviewing the updated thresholds to model 2027 outcomes for clients and employees. Areas likely to draw the most attention include:
- Roth conversions for households seeking to fill lower tax brackets efficiently
- Capital-gains timing for investors deciding when to sell appreciated assets
- Withholding updates for wage earners whose pay or bonus structures may shift them across thresholds
- Retirement withdrawals for savers balancing current tax costs against future distribution requirements
According to MarketWatch, the newly published figures are already feeding into practical planning questions, especially around how much income can be recognized without moving into a higher bracket.
A broader economic signal
The annual IRS inflation adjustment is not, by itself, a change in fiscal policy. Still, it offers a fresh reference point for how the tax code is adapting to price-level changes over time. For economists and planners, that makes the release useful as a household-finance signal even if it does not directly move stocks, bonds or currencies.
Because the update spans ordinary income, capital gains and deductions, it also highlights how tax planning is increasingly intertwined with portfolio management. In periods of unstable asset prices, tax efficiency can become more visible to investors than it is during strong rallies.
According to reports from CNBC and MarketWatch, the 2027 tax tables are now set, and the immediate takeaway is not a dramatic policy shift but a recalibrated set of thresholds that households, advisers and employers will need to incorporate into planning.
Neutral outlook: The new 2027 brackets are likely to shape household and retirement planning over the coming months, with the biggest impact concentrated in tax timing rather than immediate market moves.
MarketPro reports are AI-assisted analyses of publicly reported market news. Not investment advice.