Global Markets Daily Brief — September 24, 2026
Global markets opened September 24 with investors balancing three themes visible across the day’s wire headlines: higher-for-longer rate pressure, policy-driven technology headlines, and continued repositioning across digital assets.
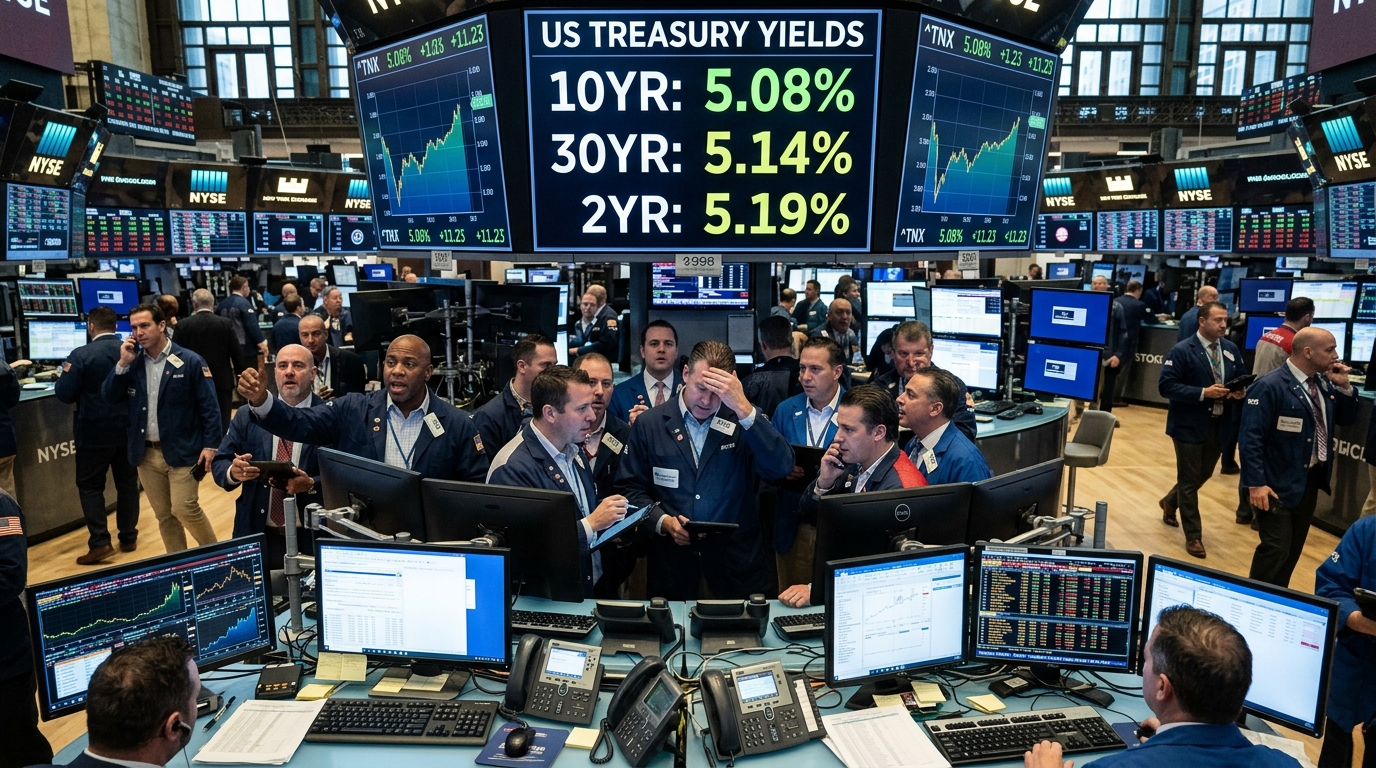
The broad macro backdrop remained defined by the bond market. CNBC reported that the 10-year U.S. Treasury yield climbed to a 19-year high, while a separate Yahoo Finance market roundup said yields later eased as investors monitored a looming Trump-Xi meeting. Taken together, those reports point to a market still centered on rate repricing, even if intraday trading turned less one-directional.
Bonds remain the main macro anchor
Even without fresh central-bank headlines in today’s wires, the move in Treasury yields continued to shape risk sentiment across asset classes. CNBC also published a companion story on what happens to the economy when yields rise sharply, reinforcing that the bond selloff is not being treated as a narrow fixed-income event. Higher benchmark yields can tighten financial conditions, influence mortgage and corporate borrowing costs, and challenge equity valuations, especially in long-duration growth sectors.
That macro picture likely mattered for stock investors reviewing a market that still appears unusually narrow under the surface. MarketWatch reported that fewer stocks are carrying the market than at any point since the dot-com peak, a sign that index-level resilience may be masking weaker breadth. In the same publication, Palantir reached its highest close of the year and Micron was described as a stock battleground as the AI narrative evolves, highlighting how concentrated leadership remains around technology and AI-linked names.
Trade diplomacy and AI policy stay in focus
Geopolitics and policy also remained central. CNBC reported that the U.S.-China trade truce was extended for two months, according to comments from Treasury Secretary Scott Bessent, as Xi began a state visit. That headline suggests some near-term policy continuity for global trade-sensitive sectors, even if the broader bilateral relationship remains strategically competitive.
At the same time, AI governance moved up the agenda. Both CNBC and MarketWatch reported that the chief executives of OpenAI and Anthropic urged greater international AI cooperation at the United Nations. The story gained added market relevance because it unfolded against political resistance from President Donald Trump, as described by CNBC. For investors, the significance is less about a single speech and more about the direction of future compliance costs, international standards, and competitive positioning for large AI developers and their enterprise partners.
Commodities hold a policy-sensitive tone
In commodities, oil and refined fuels remained heavily influenced by Washington policy debate. CNBC reported that the oil industry warned a diesel export ban would raise fuel prices as the Trump administration weighs restrictions, while Yahoo Finance separately reported that U.S. legislators are debating such a ban ahead of midterms. Those reports support the view that fuel-market intervention risk remains live, even though oil prices themselves were softer in Yahoo Finance’s broader market check.
That combination matters because a softer crude price does not automatically translate into looser refined-product balances. Trade restrictions can alter regional supply availability and price transmission even when the headline oil benchmark is under pressure.
Crypto keeps building market structure stories
Digital assets delivered another policy-and-infrastructure-heavy session. Cointelegraph reported that the NYSE and Blockchain.com are working together to bring tokenized U.S. stocks to crypto users, while Visa survey findings cited by Cointelegraph suggested stablecoin adoption could accelerate if users receive bank-like protections. Separately, Kalshi said the CFTC had not contacted it over unusual trading activity, according to Cointelegraph.
Price action, however, was less supportive. Cointelegraph reported that bitcoin fell below $84,000 and that long liquidations reached $280 million, showing that structural adoption stories can coexist with short-term volatility and leverage washouts.
Forex watch: rate differentials still matter
Today’s wire set did not include a standalone major-currency move, but the ingredients for foreign-exchange impact were clear. Elevated U.S. yields, a temporary easing in those yields later in the session, and a U.S.-China trade truce extension all matter for dollar direction and broader risk-sensitive currencies. In practical terms, Treasury moves remain the clearest cross-asset signal for FX traders until more direct currency headlines emerge.
Neutral outlook: The day’s news flow suggests markets are still being steered primarily by rates, with AI regulation, energy policy, and crypto market structure acting as important secondary drivers.
MarketPro reports are AI-assisted analyses of publicly reported market news. Not investment advice.